Four regulators, four countries, one conclusion. Customer inertia is not a side effect of the telecom market. It is part of how the market works.
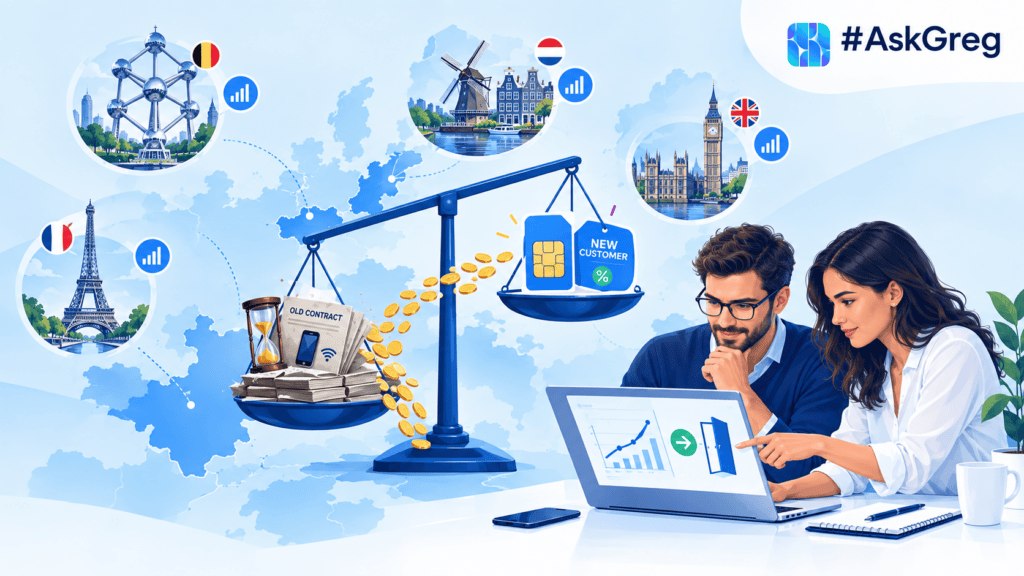
Belgium’s IBPT found that customers who accept whatever their operator offers at renewal, instead of checking if they still need the extra data, lose hundreds of euros a year. The Netherlands’ ACM went further and put a number on it: 79% of fixed internet contracts and 60% of mobile contracts are “dormant” – past their initial period, and costing their holders up to 250EUR a year more than a fresh contract would. France’s ARCEP found a paradox: 89.4% of mobile plans now carry no commitment at all, yet portability fell by a quarter in one year. And the UK’s Ofcom has spent a decade building a whole vocabulary around this – the “loyalty penalty” – priced at up to 1,114GBP a year per household across mobile, broadband and other services.
Four markets, one pattern: customers who don’t switch are subsidising the ones who do. Until recently, most operators could simply count on that.
Why this matters more than it looks
It is easy to file this under consumer-protection news. That would miss the point. What these four regulators are showing, together, is a structural feature of incumbent economics. Acquisition discounts need funding. Back-book customers on old tariffs provide it. This is not a pricing mistake by one operator. It is close to the operating model of scale telecom in mature markets.
That changes the picture for anyone who isn’t a scale incumbent.
First, inertia is now measured and named. It is no longer a private inefficiency operators can manage on their own schedule. Second, and more useful strategically: the very thing that has protected incumbent margins for years can now work against them.
From consumer protection to competitive weapon
MVNOs and alternative operators have usually treated churn and switching friction as a threat. The pattern above suggests a different move: treat anti-inertia as a selling point, not a cost to manage.
In practice, that means a few things.
Make leaving easy, and say so. Regulators are moving toward mandatory end-of-contract notices, best-tariff alerts and easier switching. An operator who already does this earns trust that a low price alone can’t buy. For an operator built around solving one specific problem well, visible fairness on exit is cheap to deliver and hard to fake.
Build onboarding for switchers, not just new customers. Every dormant contract flagged by ACM, every out-of-contract customer flagged by Ofcom, every non-switcher counted by ARCEP is a named prospect. The winners won’t be the cheapest. They’ll be the ones who make switching itself painless: number portability handled end to end, no penalty to navigate, one clear page instead of a forty-page tariff sheet.
Compete on the metric regulators are watching. If the direction of travel is mandatory comparison and proactive notification, an operator built on transparency from day one is compliant by design. That’s a story worth telling.
From best practice to hard rule
The four regulators are not at the same stage, and that gap is useful. Belgium and the Netherlands are in guidance mode: publishing data, naming the bias, encouraging better information, with enforcement building slowly. The UK has already moved to binding rules: mandatory notifications, a ban on inflation-linked price rises since January 2025, and a new Consumer Hub pushing switching data straight to consumers. France sits in between, with no mandate yet but a regulator visibly worried about falling portability.
Read together, this looks less like four separate policies and more like a staggered rollout of the same expectation across Europe. What Belgium and the Netherlands are doing today looks like where the UK stood a few years back. Operators who wait for their own regulator to catch up will end up building under pressure. Operators who build now are simply early.
The bottom line
The “loyalty penalty” that regulators frame as a consumer problem is, from an operator’s chair, a market with a price tag already attached in every country that has bothered to measure it. For an MVNO or a niche alternative operator, that’s not background noise. It’s a target list, a story to tell, and a hedge against regulation that’s coming either way.
Sources & reference points
- IBPT/BIPT :” La passivité des utilisateurs de téléphonie mobile peut leur coûter des centaines d’euros: www.ibpt.be
- ARCEP :” Observatoire des marchés des communications électroniques, T4 2025 (portability and no-commitment plan data): www.arcep.fr
- ACM (Netherlands) :” ACM: telecomaanbieders moeten consumenten duidelijker en transparanter voorlichten over vast internet: www.acm.nl
- ACM (Netherlands) :” Marktbeschouwing telecommarkt 2024 (dormant contract data : 79% fixed, 60% mobile): www.acm.nl
- Ofcom (UK) :” Consumer Hub launch and switching/money-saving guidance (2026): www.ofcom.org.uk
- Smart Data Council / UK Government : loyalty penalty estimate across mobile, broadband and mortgages : reporting via techradar.com
- Ofcom :” Ban on inflation-linked mid-contract price rises, effective January 2025: www.ofcom.org.uk
Comments are closed